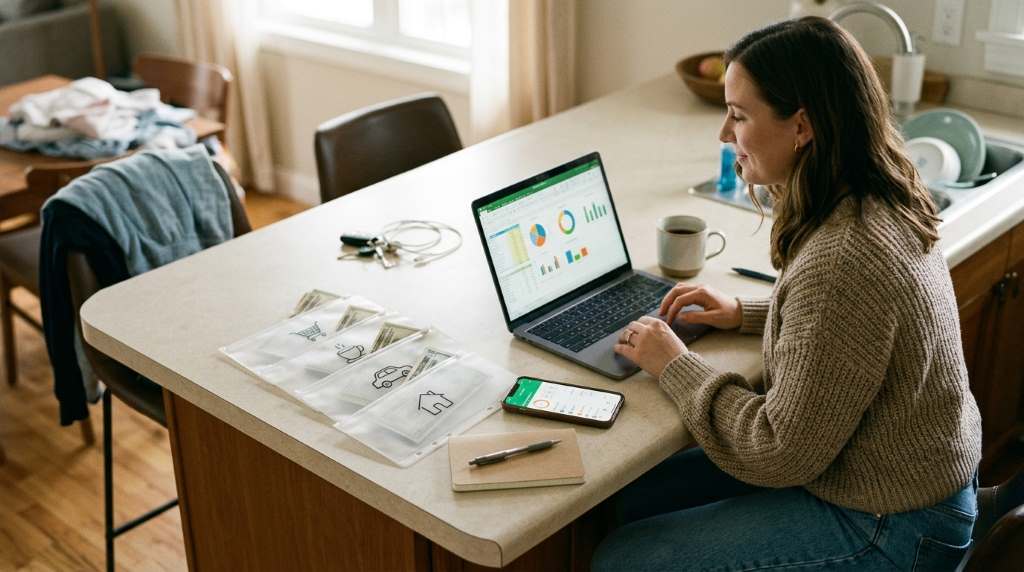
Most people do not fail at budgeting because they lack discipline. They fail because traditional budgeting is exhausting. Between work deadlines, family responsibilities, and just trying to sleep enough, sitting down with a spreadsheet every evening feels impossible. According to a 2023 survey by the National Financial Educators Council, financial stress costs Americans an average of $1,819 per year in lost productivity and poor decisions. Meanwhile, research from the Consumer Financial Protection Bureau confirms that people who follow even a simple budgeting method are significantly more likely to build savings and avoid debt. The good news is that a lazy monthly budget system for busy people does not require daily effort or financial expertise. It requires a smart setup and a few good habits you do once and mostly forget.
Why Traditional Budgets Fail Busy People
Traditional budgeting advice sounds simple on paper. Track every coffee. Categorize every transaction. Review your spending weekly. In reality, these habits collapse fast for anyone with a packed schedule.
The problem is not your willpower. The problem is the system itself. Most budgeting methods were designed for people with extra time, and that description fits very few adults today.
Here is what typically happens. You start strong in January. By February, you miss a few days of tracking. By March, the whole thing falls apart and you feel guilty. That guilt often leads to even worse financial decisions, which is exactly the opposite of the goal.
A lazy budget system works differently. Instead of relying on daily attention, it uses automation, simple rules, and built-in guardrails. You spend a couple of hours setting it up once, then check in for just fifteen minutes each month. That is it.
The Core Philosophy Behind the Lazy Budget
The lazy monthly budget system runs on three ideas: automation, simplicity, and forgiveness.
Automation handles the mechanical parts so you do not have to remember them. Simplicity means fewer categories, fewer decisions, and fewer points of failure. Forgiveness means the system accounts for imperfect months without punishing you.
Think of it like a self-watering planter. You fill it up, set it, and the plant mostly takes care of itself. You still check in occasionally, but you are not out there with a watering can every single day.
This mindset shift is important. You are not trying to control every dollar obsessively. You are building a system that guides your money in the right direction most of the time. Most of the time is enough to build real financial stability.
Step One: Know Your Three Core Numbers
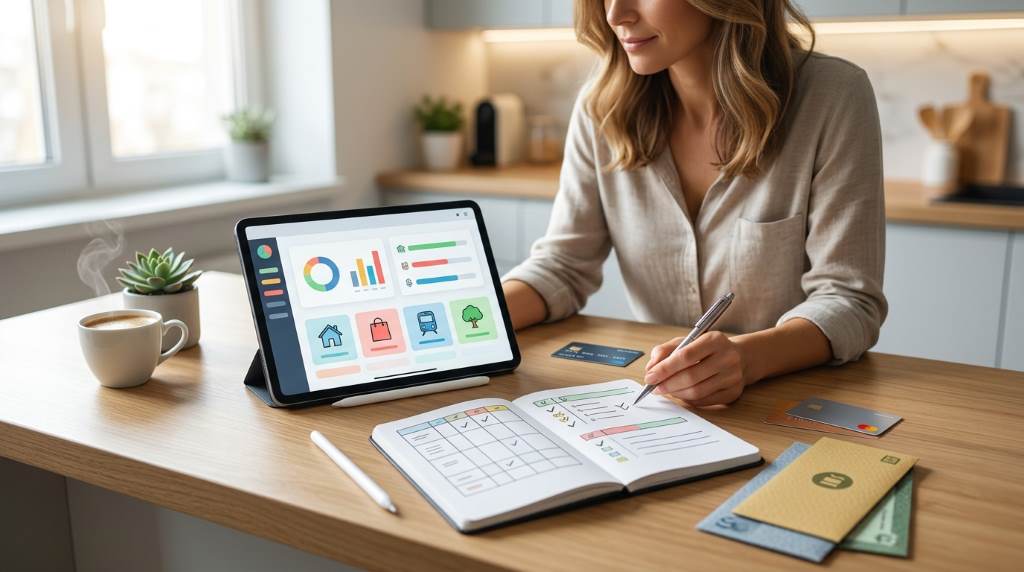
Before you automate anything, you need three numbers. These form the foundation of your entire lazy budget.
Your monthly take-home income. This is the real number after taxes and any automatic deductions. If your income varies, use the average of your last three months as your working figure.
Your fixed monthly expenses. These are bills that stay the same each month: rent or mortgage, car payment, insurance premiums, subscription services, loan minimums. Add them all up.
Your savings target. Decide a percentage of your income you want to save before spending on anything else. Even ten percent makes a substantial difference over time.
Once you have these three numbers, subtract your fixed expenses and savings target from your income. Whatever remains is your flexible spending pool. This pool covers groceries, dining out, entertainment, clothing, and everything else that varies month to month.
You do not need to track every item within that pool obsessively. You just need to know when you are approaching the limit.
Step Two: Build the Two-Account System
The backbone of a lazy monthly budget is a simple two-account structure. Many financial experts recommend this approach because it removes the need for constant decision-making.
Account One: Bills and Savings. This account receives your full paycheck. From here, automatic transfers handle your fixed bills, your savings contribution, and your investment accounts if you have them. You set these transfers up once and they run in the background forever.
Account Two: Spending Money. On payday, a set amount automatically moves from Account One into Account Two. This is your flexible spending pool. Everything else: groceries, restaurants, shopping, comes out of this account. When it gets low, you slow down. When the month ends, whatever is left rolls over as a small cushion.
This structure makes overspending much harder. Your rent money and savings are untouchable in Account One. You can only spend what lands in Account Two. No math required, no daily tracking necessary.
Setting this up takes about an hour at your bank or credit union. Many banks offer this kind of automatic transfer scheduling for free. Some people use a separate checking account through a different bank for their spending money, which adds a small psychological barrier that prevents impulsive dipping into bills money.
Step Three: Automate Your Savings First
The single most powerful habit in any budget system is paying yourself first. Most people spend money and save whatever is left. Because something always comes up, whatever is left is usually nothing.
Flip that order completely. On payday, your savings transfer happens before you see the money in your spending account. Because it moves automatically, you never feel the loss. Within a few months, you genuinely stop noticing it is gone.
Start with whatever percentage feels manageable. Three percent works. Five percent is better. Ten percent is the widely cited recommendation from personal finance research. The exact number matters less than the consistency. You can always increase the percentage later when you get comfortable.
Set up these automatic transfers to land in a high-yield savings account or a separate emergency fund. Keeping this money at a different bank than your daily spending account adds friction that prevents impulsive withdrawals.
If your employer offers a retirement plan with matching contributions, prioritize that above everything else. Employer matching is effectively free money, and no savings account can compete with that return.
Step Four: Use the 50/30/20 Rule as a Loose Framework
You do not need a custom spreadsheet with thirty-seven categories. The 50/30/20 framework gives you a simple mental model that works for most income levels.
Fifty percent of your take-home pay covers needs: housing, utilities, groceries, transportation, insurance, and minimum debt payments. Thirty percent covers wants: dining out, streaming services, hobbies, and non-essential shopping. Twenty percent goes toward savings and extra debt payments.
This is a guideline, not a law. If you live in a high-cost city, your housing alone might consume forty percent of income. Adjust the other categories accordingly. The framework is a compass, not a contract.
The key advantage of this approach for busy people is its flexibility. You do not audit individual transactions. You simply check once a month whether your spending roughly matches these proportions. If something looks wildly off, you investigate. If everything looks reasonable, you move on with your day.
Step Five: Pick One Simple Tracking Method
Even a lazy budget needs some visibility. Without occasional check-ins, you lose awareness and small spending creep turns into a big problem.
The goal is not perfect tracking. The goal is awareness with minimum effort. Here are three options depending on your personality.
The bank balance method. Check your spending account balance once a week. If it looks on track for the month, do nothing. If it looks low, slow down discretionary spending for the remaining days. This takes thirty seconds.
The monthly statement review. Once a month, spend fifteen minutes scrolling through your bank or credit card statement. Look for anything surprising. Cancel any subscriptions you forgot about. Note whether your total spending fits within your flexible spending pool. Done.
A simple budgeting app. Apps like those that connect to your bank and categorize transactions automatically handle the tracking for you. You review a summary rather than individual transactions. This requires minimal effort after the initial setup.
Choose whichever method you will actually stick with. Consistency beats sophistication every single time.
Step Six: Create a Monthly Budget Reset Ritual
Because this system is monthly rather than daily, you need one short monthly check-in to keep things on track. Think of it as a fifteen-minute money date with yourself.
Pick a consistent time: the first Sunday of every month, payday afternoon, or any recurring slot that works for your schedule. Pour a coffee, open your bank app, and run through a short checklist.
The monthly reset checklist looks like this:
- Check that all automatic transfers ran correctly.
- Review last month’s spending account activity for anything unusual.
- Look for subscriptions or recurring charges you no longer use.
- Note whether your savings balance grew as expected.
- Adjust your flexible spending amount if your income or bills changed.
That is genuinely the entire process. Fifteen minutes once a month is all this system asks of you after the initial setup. Most months, everything will look fine and you will finish in ten minutes.
Handling Variable Income With a Lazy Budget
Freelancers, gig workers, and anyone with irregular income need a slightly adjusted approach. The core structure stays the same, but you base everything on your lowest expected monthly income rather than an average.
Calculate your baseline: the minimum you reliably earn each month even in slow periods. Build your fixed expenses and savings transfers around that number. In stronger months, the extra income either goes directly to savings or funds your flexible spending account with a bonus top-up.
This approach prevents the common mistake of spending like a good month will last forever. Your system protects you during slow months automatically, because it was always built around that conservative floor.
Some people with variable income find it helpful to pay themselves a consistent monthly salary from a business account. They deposit all client payments into the business account, then transfer a steady amount to personal accounts each month. This smooths out income variation and makes the lazy budget work exactly as described above.
Common Lazy Budget Pitfalls and How to Avoid Them
Even simple systems have failure points. Being aware of them in advance makes a real difference.
Lifestyle creep. As income rises, spending tends to rise with it. Counter this by automatically increasing your savings percentage whenever you get a raise. If your income goes up by five percent, direct at least half of that increase toward savings before adjusting your lifestyle spending.
Ignoring irregular expenses. Annual expenses like car registration, holiday gifts, or insurance premiums can feel like emergencies when they arrive. They are not emergencies. They are predictable. Add up all your annual expenses, divide by twelve, and add that amount to your monthly savings transfer into a dedicated sinking fund. When the bills arrive, the money is already there.
Setting and completely forgetting. Automation is powerful but not infallible. Bank accounts change, subscriptions sneak in, and direct deposits occasionally glitch. Your monthly check-in exists precisely to catch these small issues before they become larger ones.
Starting with too many categories. If you try to track groceries separately from household supplies separately from dining out separately from coffee, you will give up. Start with just three buckets: fixed expenses, savings, and everything else. You can refine later if you want to, but you probably will not need to.
The Emotional Side of a Lazy Budget
Money and emotions are deeply connected. One underrated benefit of the lazy budget system is that it reduces financial anxiety without requiring obsessive monitoring.
When your savings transfer runs automatically and your bills are covered before you touch your paycheck, the low-grade financial dread that many people carry quietly disappears. You know your obligations are handled. Whatever is in your spending account is genuinely yours to use without guilt.
This psychological shift is not trivial. Financial stress affects sleep, relationships, and work performance. Reducing that stress even modestly creates ripple effects throughout your life. A simple budget system you actually follow delivers far more value than a complex system you abandon after three weeks.
Conclusion
The lazy monthly budget system for busy people works because it removes friction from good financial behavior. Automation takes the daily decision-making off your plate. Simple rules replace complex spreadsheets. Regular check-ins keep you aware without consuming your time.
You do not need to track every dollar or review your spending daily. You need a reliable structure that moves your money where it belongs before you have a chance to spend it impulsively, a spending account that acts as a natural guardrail, and a fifteen-minute monthly review to catch anything unusual.
Start this week by calculating your three core numbers. Open a second checking account if you do not already have one. Set up your first automatic savings transfer, even if it is just a small amount. The system compounds over time, and the earlier you start, the more it works in your favor.
Small, consistent action beats perfect planning every time. Your future self will thank you for the ten minutes you spend setting this up today.
Frequently Asked Questions
What is the easiest budget method for someone with no time?
The two-account system with automatic transfers is the simplest starting point for busy people.
How much should I save each month as a beginner?
Start with five to ten percent of your take-home pay and increase it gradually over time.
Can a lazy budget work if my income changes every month?
Yes, base your budget on your lowest expected monthly income and treat extra earnings as a bonus.
How often should I actually check my budget?
One fifteen-minute monthly review is enough to keep the lazy budget system running well.
What app works best for a low-effort monthly budget?
Any app that connects to your bank and auto-categorizes transactions reduces your manual work significantly.
Related Reads
Explore: How to Create a Business Continuity Strategy Focused on Human Capital Risks
Explore: Business Loan Approval Tips With No Money Down
Read more: 15 Best AI Tools to Build a Million-Dollar Business Without Employees in 2025